AT&T Inc. (NYSE: T) reported third-quarter results, extending the momentum of its investment-led strategy as it delivers advanced connectivity to more consumers and businesses. The Company achieved a record quarter for Advanced Connectivity internet net adds and grew its base of high-value converged relationships by approximately 350,000. The results demonstrate the value of AT&T’s differentiated fiber and 5G portfolio as it continues to accelerate growth in consolidated service revenue and improve operating efficiency, driving durable long-term profitability.
"We are growing valuable customer relationships as more homes and businesses choose AT&T for all their advanced connectivity needs across both internet and on-the-go wireless,” said John Stankey, AT&T Chairman and CEO. “Our asset base positions us well for the AI era, with a leading position in fiber – the best technology available. We’re building the nation’s strongest network, backed by America’s Best Guarantee, to deliver faster, more reliable and more accessible connectivity.”
Third-Quarter 2026 Consolidated Financial Results1
- Revenues totaled $32.3 billion, up 5.3% year over year
- Diluted EPS from continuing operations was $0.13, which includes a non-cash impairment charge associated with the Company’s held-for-sale Mexico wireless business as well as employee separation charges, versus $1.29 in the year-ago quarter, which included a gain recognized on the sale of the DIRECTV investment; adjusted EPS* was $0.65, versus $0.54 in the year-ago quarter
- Operating income was $4.1 billion; adjusted operating income* was $7.6 billion
- Income from continuing operations was $1.3 billion; adjusted EBITDA* was $12.5 billion, up 5.4% year over year
- Cash from operating activities from continuing operations was $10.5 billion, versus $10.2 billion in the year-ago quarter
- Capital expenditures related to continuing operations were $5.1 billion; capital investment* was $5.6 billion
- Free cash flow* was $5.0 billion, versus $4.9 billion in the year-ago quarter
Third-Quarter 2026 Highlights
- Second consecutive quarter with over 1 million Advanced Connectivity customer additions, driven by accelerated internet net adds and solid postpaid phone net adds
- Advanced Connectivity service revenue of $23.9 billion, up 6.1% year over year
- Advanced Connectivity operating income of $7.6 billion, up 18.9% year over year, with EBITDA* of $12.3 billion, up 7.3%
- 42.8% of households with AT&T’s advanced home internet services also chose AT&T wireless2
- 769,000 total consumer and business Advanced Connectivity internet net adds, a record quarter, including 442,000 fiber and 327,000 fixed wireless
- 379,000 postpaid phone net adds with postpaid phone churn of 0.92%
- Reached more than 39 million total consumer and business locations with fiber; the Company remains on track to reach over 40 million total fiber locations by the end of 2026 and more than 60 million locations by the end of 20303
- Returned approximately $4.8 billion to shareholders, including $2.8 billion in common share repurchases
Financial Outlook and Capital Allocation Plan
AT&T is increasing its outlook for 2026 adjusted EPS* and lowering its long-term outlook for capital investment. AT&T maintains its long-term outlook for improved growth in adjusted EBITDA* and adjusted EPS* and higher free cash flow* through 2028, its plans to return $45 billion+ to shareholders during 2026-2028 through dividends and share repurchases, and an expectation that its net debt-to-adjusted EBITDA ratio* will return to a level consistent with its target in the 2.5x range during 2029.
AT&T’s long-term outlook is presented on a continuing operations basis and, for 2027-2028, excludes AT&T Mexico, which it has agreed to sell to Grupo Televisa and Fintech Holdings.
The Company’s long-term outlook for 2026-2028 includes4:
- Service revenue growth in the low-single-digit range annually
- Advanced Connectivity service revenue growth in the mid-single-digit range annually, including expected growth of 5%+ in 2026
- Legacy service revenue decline of 20%+ in 2026 and be immaterial by the end of 2029
- Adjusted EBITDA* growth in the upper portion of the 3% to 4% range in 2026, improving to 5% or better in 2028
- Advanced Connectivity EBITDA* growth in the mid-to-high-single-digit range annually, including expected growth of 6%+ in 2026
- Legacy EBITDA* expected to turn negative after 2027, until AT&T has substantially eliminated direct costs associated with operating its copper-based network5
- Adjusted EPS* in the $2.40 range in 2026 with a double-digit 3-year CAGR through 2028
- Capital investment* in the $23 billion to $24 billion range in 2026 and in the $22 billion to $23 billion range annually in 2027 and 2028
- Free cash flow* of $18 billion+ in 2026, $19 billion+ in 2027, and $21 billion+ in 2028
- Strong capital returns, including plans to maintain its current annualized common stock dividend of $1.11 per share and $24 billion+ of share repurchases, including approximately $10 billion during 2026
Note: AT&T’s third-quarter 2026 earnings conference call will be webcast at 8:30 a.m. ET on Wednesday, October 21, 2026. The webcast and related materials, including financial highlights, will be available at investors.att.com.
Detailed Third-Quarter 2026 Consolidated Financial Results
- Revenues for the third quarter totaled $32.3 billion, versus $30.7 billion in the year-ago quarter, up 5.3%. This was largely due to growth in Advanced Connectivity wireless service and equipment revenues, and fiber revenues, which include the impact of the Company’s first-quarter acquisition of Lumen’s mass markets fiber business. Operating revenues in Latin America were also higher due to favorable foreign exchange impacts and growth in postpaid revenues. Offsetting the increases were lower Legacy revenues from lower demand for services as the Company continues to decommission its copper-based network.
- Operating expenses were $28.2 billion, versus $24.6 billion in the year-ago quarter. Operating expenses increased primarily due to a non-cash impairment charge associated with the Company’s held-for-sale Mexico wireless business of $2.6 billion, employee separation charges, increased wireless equipment costs, as well as higher advertising and higher bad debt expenses driven by subscriber growth. The increase was also due to incremental customer costs related to the acquired mass markets fiber business. These increases were partially offset by cost reductions from transformation initiatives and apportioned legal settlements in the prior-year period. Depreciation expense was also lower year over year from fully depreciated legacy assets, partially offset by ongoing capital spending for strategic initiatives.
- Operating income was $4.1 billion, versus $6.1 billion in the year-ago quarter. Adjusted operating income* was $7.6 billion, versus $6.6 billion in the year-ago quarter.
- Income from continuing operations was $1.3 billion, versus $9.7 billion in the year-ago quarter.
- Income from continuing operations attributable to common stock was $0.9 billion, versus $9.3 billion in the year-ago quarter. Earnings per diluted common share from continuing operations was $0.13, versus $1.29 in the year-ago quarter, which included a gain recognized on the sale of the DIRECTV investment. Adjusting for $0.52, which includes a non-cash impairment charge associated with the held-for-sale Mexico wireless business, employee separation charges, and other items, adjusted earnings per diluted common share* was $0.65, versus $0.54 in the year-ago quarter.
- Adjusted EBITDA* was $12.5 billion, versus $11.9 billion in the year-ago quarter.
- Cash from operating activities from continuing operations was $10.5 billion, versus $10.2 billion in the year-ago quarter, which included voluntary pension plan contributions. The increase also reflects timing of working capital payments.
- Capital expenditures related to continuing operations were $5.1 billion, versus $4.9 billion in the year-ago quarter. Capital investment* totaled $5.6 billion, versus $5.3 billion in the year-ago quarter. Cash payments for vendor financing totaled $0.5 billion, versus $0.4 billion in the year-ago quarter.
- Free cash flow* was $5.0 billion, versus $4.9 billion in the year-ago quarter.
- Total debt was $159.6 billion at the end of the third quarter and net debt* was $149.8 billion, both reflecting a sequential increase related to the closing of the EchoStar spectrum transaction.
AT&T Third-Quarter 2026 Segment Results6
Advanced Connectivity service revenues grew 6.1% year over year, driving growth in operating income of 18.9% and EBITDA* of 7.3%. Internet net adds were 769,000 – comprised of 442,000 fiber and 327,000 fixed wireless – and postpaid phone net adds were 379,000.
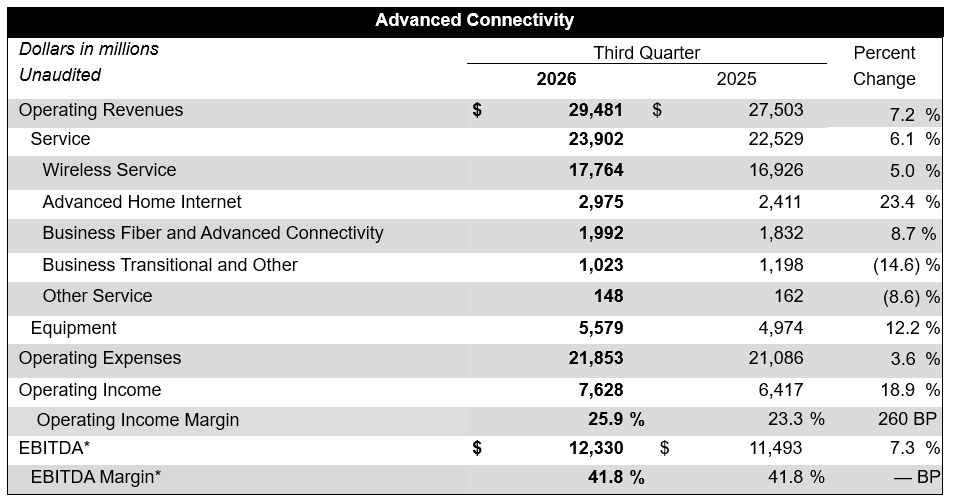
Advanced Connectivity segment revenues grew 7.2% year over year, driven by service revenue growth of 6.1% and higher equipment revenue. Wireless service revenue increased due to growth in retail wireless subscribers in underpenetrated categories and converged accounts, and pricing actions that were partially offset by promotional discounts on wireless subscriber additions. Advanced home internet revenue growth, which included an impact from the acquired mass markets fiber business that closed in the first quarter, reflects increases in fiber and AT&T Internet Air revenues. Business fiber and advanced connectivity revenues increased largely due to higher fiber and fixed wireless revenues. Business transitional and other revenues decreased due to lower demand for virtual private network and wholesale services.
Operating expenses were up 3.6% year over year, due to increased wireless equipment costs, higher advertising expense, incremental customer costs related to the acquired mass markets fiber business, and higher bad debt expenses driven by subscriber growth. These increases were partially offset by cost reductions from transformation initiatives. Additionally, depreciation expense decreased year over year from fully depreciated legacy assets, partially offset by ongoing capital spending for strategic initiatives.
Operating income was $7.6 billion, up 18.9% year over year. EBITDA* was $12.3 billion, up $837 million year over year.
Legacy revenues continued to decline year over year in line with AT&T’s goal to decommission the large majority of its copper-based network by the end of 2029.
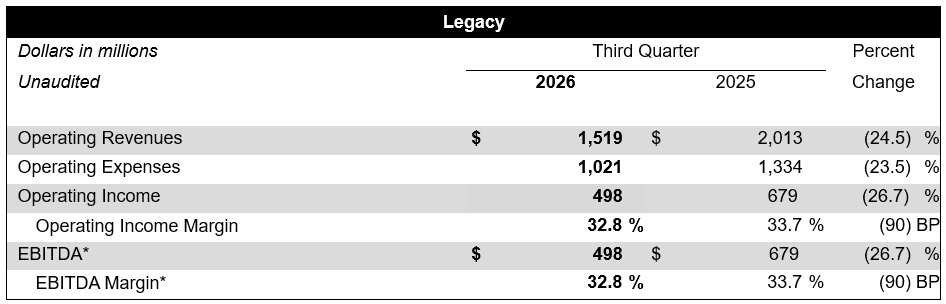
Legacy segment revenues were down 24.5% year over year, primarily due to lower demand for services as the Company continues to decommission its copper-based network. Operating expenses, which represent direct operating costs, were $1.0 billion, down 23.5% year over year. Expense declines were primarily driven by lower personnel and other costs resulting from the decommissioning of the copper-based network, and lower fulfillment cost amortization, partially offset by favorable vendor settlements in the prior-year period. Operating income and EBITDA* were $498 million, down $181 million year over year.
On October 13, 2026, AT&T entered into an agreement to sell its Mexico wireless business, which is the entirety of the Latin America segment. AT&T applied held-for-sale accounting in continuing operations as of September 30, 2026, and recorded a non-cash impairment charge of $2.6 billion at Corporate and Other that did not impact third-quarter segment results. AT&T will continue to present results within the Latin America segment.
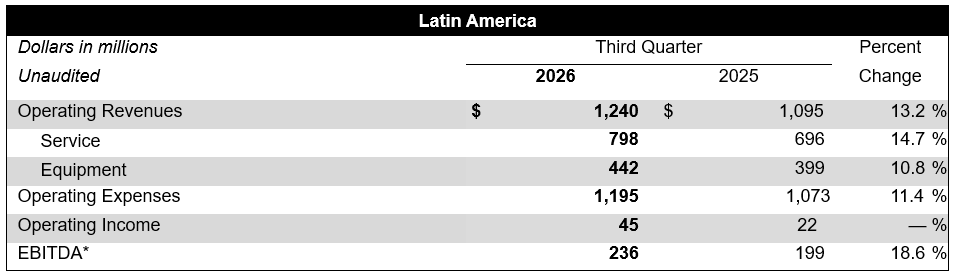
Latin America segment revenues were up 13.2% year over year, primarily driven by favorable foreign exchange rates and postpaid wireless subscriber growth. Operating expenses were up 11.4% year over year due to unfavorable foreign exchange rates, higher bad debt expenses, and higher equipment costs. Operating income was $45 million, up $23 million year over year. EBITDA* was $236 million, up $37 million year over year.
Read more Investor Relations news